Best Payment Processing for Contractors (2026 Guide)
Whether you’re an electrician, plumber, HVAC company, roofer, landscaper, painter, home renovator, or general contractor, getting paid quickly matters. Contractors often pay for labour,…
B2B payments remain one of the largest and least consumerized segments of global commerce, but the data in 2026 shows steady, measurable change. Trade credit terms like Net30 and Net60 still dominate invoice-based payments, while digital methods, including credit cards, are growing faster than any other rail. The result is a hybrid environment where legacy practices persist, but behavior is increasingly shaped by speed, automation, and working-capital optimization.
This article focuses specifically on what the data says, not opinions, about how B2B payments are actually made in 2026.
The global B2B payments market continues to dwarf consumer payments by value. In 2026, total annual B2B payment volume is estimated at $150T–$180T USD, representing over 85% of global payment value, driven by wholesale trade, manufacturing, professional services, and cross-border commerce. By comparison, consumer payments total roughly $20T–$30T USD annually, despite accounting for the majority of payment transactions worldwide.
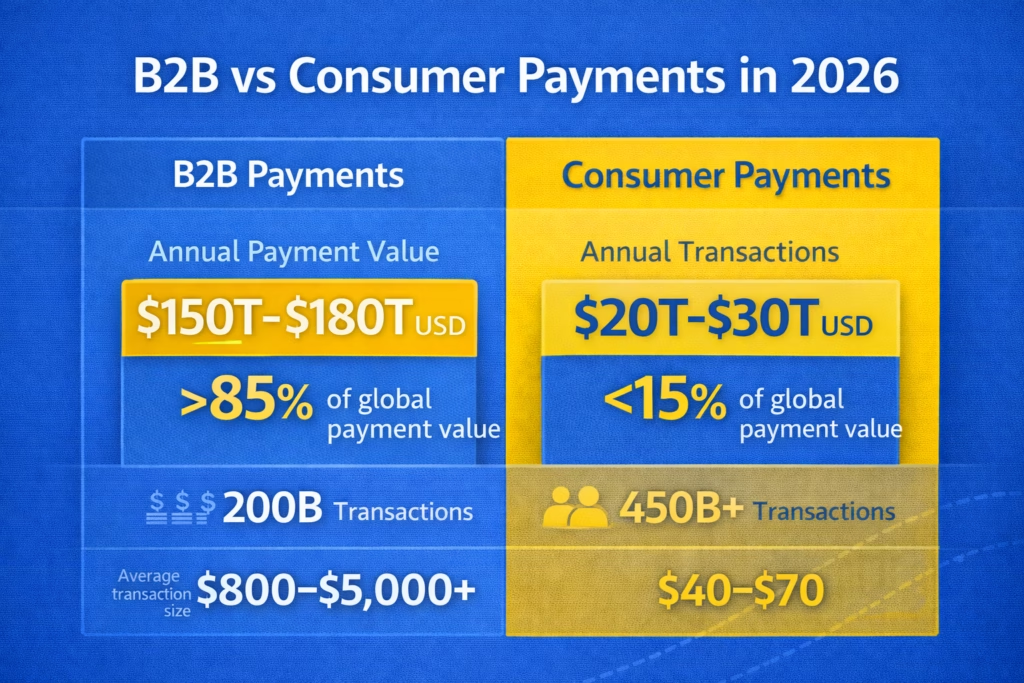
Several structural data points stand out:
Despite this scale, modernization is uneven, which is why payment mix statistics matter.
Trade credit remains the backbone of B2B payments. In 2026, Net30 and Net60 are still the most commonly offered invoice terms across North America and Europe.
Data across multiple industry surveys shows:
Payment behavior diverges meaningfully from invoice terms:
These statistics explain why suppliers increasingly seek faster or guaranteed settlement options alongside trade credit.
Days Sales Outstanding (DSO), which measures the average number of days it takes a business to collect payment after a sale, remains one of the most closely tracked B2B finance metrics, and the data in 2026 shows persistent inefficiencies.
Median DSO benchmarks by segment:
Industries with the highest DSOs include construction, manufacturing, logistics, and professional services. Businesses that rely exclusively on invoice-based Net Terms typically report DSOs 12–18 days higher than peers offering digital payment alternatives, including cards.
Digital payment adoption continues to rise, but legacy rails remain significant. In 2026, the shift is best described as incremental but durable.
Key adoption statistics:
Automation impacts efficiency materially:
Credit cards remain underutilized relative to their advantages, but adoption continues to climb. In 2026, cards account for approximately 8–12% of B2B payment volume, but 20–25% of transaction count, skewed toward smaller and recurring payments.
Usage patterns show clear trends:
For buyers, cards function as embedded credit:
For suppliers, the financial impact is measurable:
Rather than competing directly, Net Terms and cards increasingly coexist. Data shows buyers choose based on transaction size, urgency, and internal approval workflows.
Comparative statistics:
Suppliers offering both options report:
The statistics point to a clear conclusion. B2B payments are not abandoning Net30 or Net60, but they are becoming more flexible, data-driven, and digitally optimized.
Businesses winning in 2026:
Whether you’re an electrician, plumber, HVAC company, roofer, landscaper, painter, home renovator, or general contractor, getting paid quickly matters. Contractors often pay for labour,…
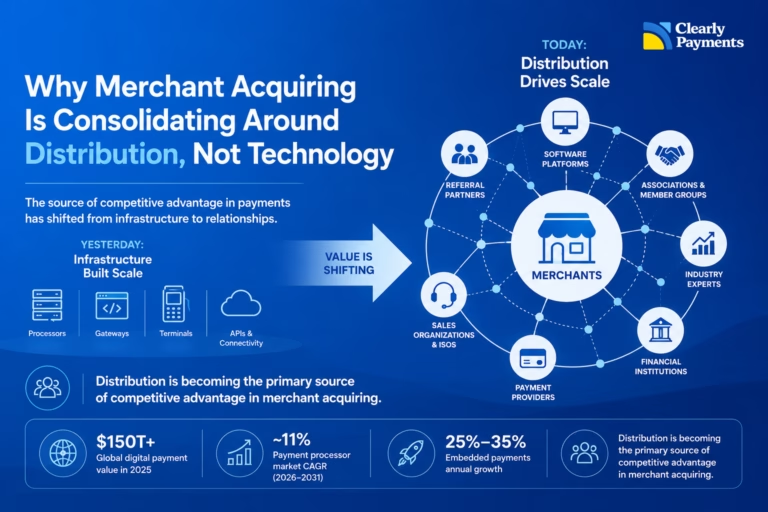
The payments industry has spent decades investing in technology. Processors built massive infrastructure platforms. Acquirers invested billions in connectivity, security, compliance, hardware certifications, and…
Accepting credit cards is essential for most businesses today, but the fees can quietly add up. Many merchants assume payment processing rates are fixed,…